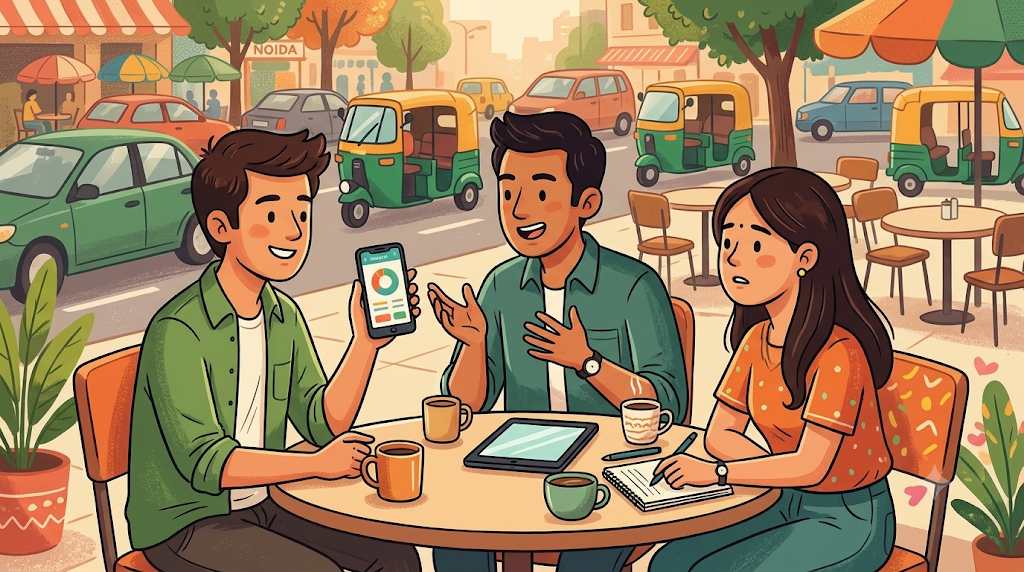
Rahul sipping hot mocha at Starbucks aggressively tapped his mobile phone while his friends watched. Irritated Amit quipped “why are you on phone, when we are together for a catch-up.” Rahul too engrossed in his own things, ignored. Friends watched irritably.
“Voila” suddenly Rahul jumped “I just linked my entire ₹15 Lakh mutual fund portfolio to this new Mutual Fund app”. Elated Rahul rotated his phone to show a colourful dashboard to his friends. “It took me two minutes to create an account and analyse my portfolio.” He added – “The app found a few critical issues. Also 7 of 9 funds held by me are underperforming their benchmarks. It identified composition issues and highlighted concerns about their growth.”
Sneha leaned forward to look at the mobile screen. “It is really impressive, but why are they giving free advice to fix our investments? There must be some catch.”
Amit, who had been quietly stirring his cappuccino with extra sugar, looked up and commented. “That is the question Rahul should ask. I feel they do it to get business from Rahul. Two minutes is good to make Maggi, not to change your portfolio” Rahul frowned at the comment. Clearly, he was not happy.
Portfolio Trackers
Rahul with his raised eye brows, pulled back his phone. “It is just an artificial intelligence-based programme. There is nothing wrong.”
“There is nothing wrong with these apps if used prudently,” Amit shifted to his usual analytical mode. “These fintech platforms offer aggregation and tracking to collate your financial data that comes handy. Their suggestions can also be useful for the people who have limited time or interest in tracking themselves.”
Amit also raised privacy concerns – “However, there is trouble when they know your exact financial position and unnecessarily push mutual funds under their distributor code. It may start with free discussion with an expert wealth advisor. Accepting their ‘suggestions’ generate trailing commissions for them.”
Amit pointed to the screen. ” When you shuffle your portfolio, you move to their distributors code. It is money for them – not once but every year until you sell. Also, things aggravate when they cross-sell other high-margin products like credit cards or insurances or loans against your mutual funds. “
How to Use Wealth-Tech Apps Intelligently
“So, should I delete the app?” Rahul asked, in a sad tone.
“No, there is no need discard them in entirety,” Amit countered. “You may use them. In fact, I have collated all my info through my banking app. Banks may also extend such facility.” He added. “These aggregators show where our investments are and help us to revisit them, give a clean view of asset allocation and identify creases to consider and iron out.”
Momentum and Contra
Sneha chimed in. “But what if the app is right? I haven’t touched my SIPs in years. Shouldn’t we be cleaning up our portfolios?”
“Of course,” Amit nodded. “Some shuffle is required from time to time. The market is not static. But you make those changes based on structural fundamentals, not because you get a push notification about a ‘top performing’ fund.”
“Like what?” Rahul asked.
“Like shifting sectoral trends and macroeconomic indicators,” Amit said. “This is where you need to understand the concept of momentum and contra. The market moves in cycles, and the winners and losers constantly change places. An app’s algorithm may chase momentum and often make suggestions based on trailing returns. It is easier for them to make you act to replace losing funds. Human psyche works in that fashion. If you buy the sector that are currently near their peaks, you may not get the returns that you are expecting.”
Amit pointing towards phone to emphasise. “A smart investor also considers what is fundamentally strong but currently out of favour. There are always a few sectors that are beaten down due to temporary headwinds, but with solid core businesses. There are also some industries that are more cyclical. Amit added. “I personally like investing in sugar and steel share when they are not doing well. That is a contra bet. You can do the same with sectoral funds. You buy when things look gloomy and hold until the cycle turns. The apps may tell you to sell your underperformers, even if they are at the perfect valuation to buy more.”
Rahul looked down at his phone, his thumb hovering over the app’s ‘Rebalance’ button. He locked the screen and put the phone in his pocket.
“Alright,” Rahul smiled. “I will keep the dashboard for the data. But I am keeping my money exactly where until I check the fundamentals, and form my own opinion.”
The smart investor’s strategy using app aggregators
- Install only if you feel the need: Do not install these app until you genuinely feel the need for them.
- Consume the suggestions: In case you install, let the app crunch the numbers and identify areas for improvements.
- Decide independently: Do not blindly hit the “Rebalance” button on their platform. However, also do not brush aside their suggestions. Study, analyse and take your own decisions.
- Execute through your preferred channel: Place the actual buy and sell orders on your own terms and through your own preferred channel. You may trade through them or any other SEBI registered distributor. You may also invest using direct mode where expenses are less.